
Article last updated 6 October 2026.
Summer is winding down. A summer hotter than I can remember, with a reliability of sunshine and temperature I’ve never experienced in this country. There was no decision to be made about what to wear, whether to take an umbrella, or back-up plans for the picnic. Of course, all things must pass, and as we head into autumn I’m taking a positive: mushroom season.
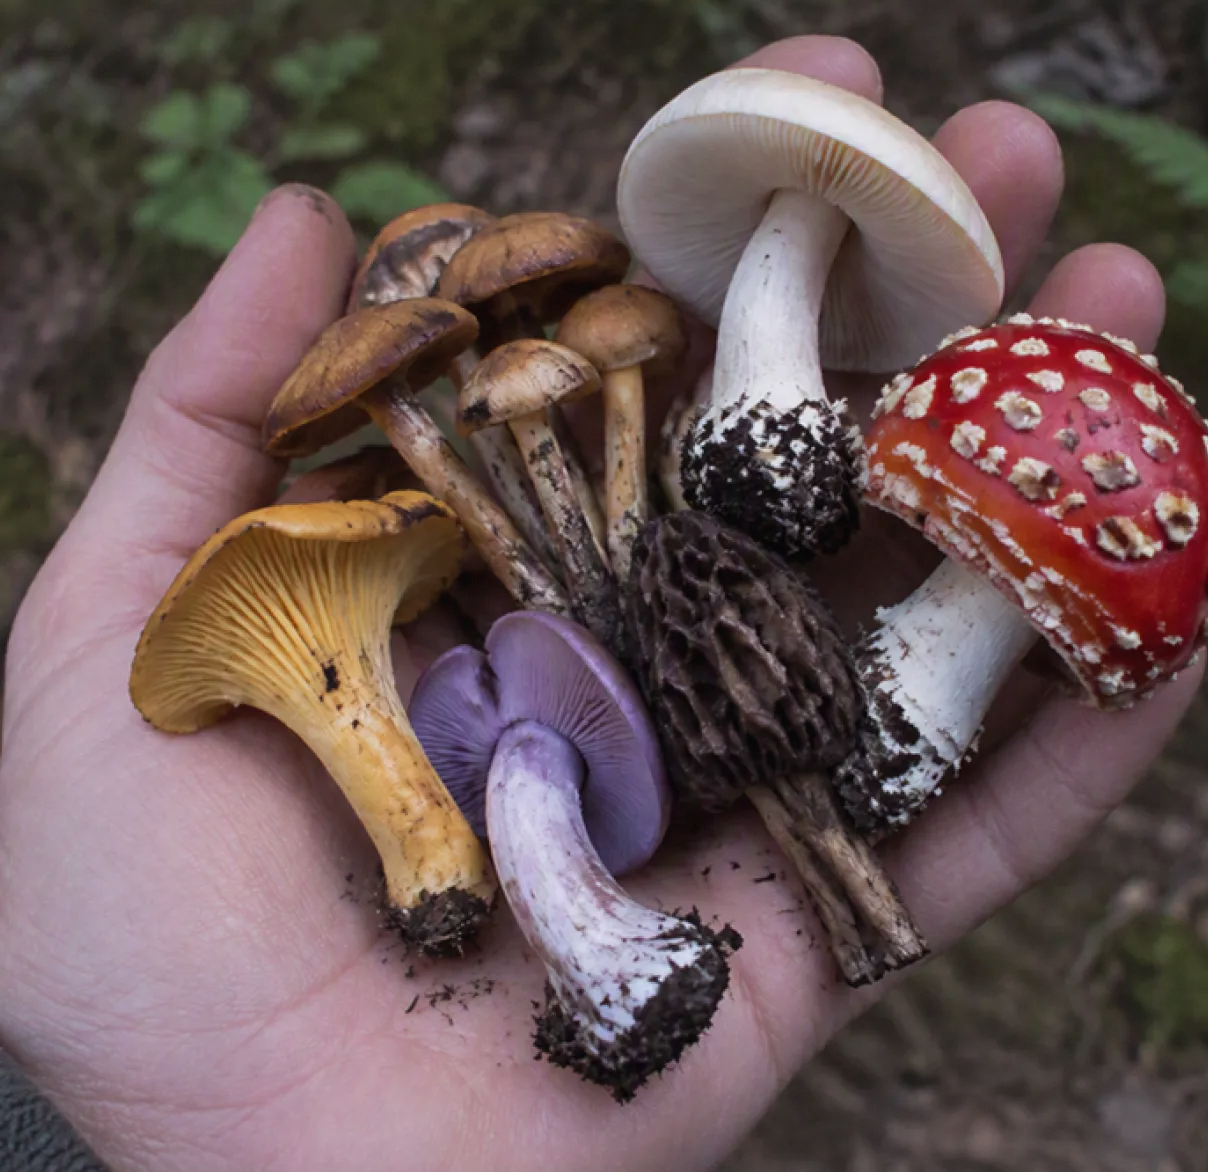
As I’ve become older, and sadder, I’ve become a little obsessed with mushroom foraging. Of course, it does come with some risk. Many mushrooms look very similar, but the consequences of ingesting them can be a little varied – from high health benefits and a tasty side dish to wild hallucinations or slow and painful death!
Buying government bonds right now feels a little like mushroom picking. They arguably look pretty tasty right now – high yields of 5.0-5.5%, a good chunk higher than where inflation currently sits, providing you with a reasonably attractive real yield. And now that they’re back at higher starting yields, they should again be reliable safe-haven assets that should rise in value during any growth scares, bursting bubbles, or credit crises. Yet right now they’re also in danger of being a core driver of why stocks and other ‘risk’ assets might fall. As bond yields rise, they act as a headwind to growth, driving up the cost of borrowing for governments, companies and consumers alike. Anyone trying to sell a flat or house in the UK right now can probably attest to the negative impact of higher rates. If anyone is looking for a flat in Croydon, someone in our team would love to hear from you! The higher rates also reduce the value of future cashflows of companies, sending their share prices lower. This is particularly acute for growth companies that aren’t growing at exponential rates.
Mushrooming debt
Often, equity markets will overlook day-to-day moves in government bond yields. But over the last few years, as the 10-year US government bond yield has approached and now edged beyond 5%, it has typically been negative for equities, and we are starting to enter that territory.
So what exactly is causing these bond yields to move higher?
-
Inflation is the obvious candidate. The oil price has gone from $60 to $100 today (via $120) as the Iran war greatly reduces supply through the Strait of Hormuz. It has an immediate inflationary impact, and the longer the oil price stays elevated, the greater concerns will grow that this cost will start to be passed through to the prices of goods and services, creating a broader-based inflationary issue. And the end products from crude oil, such as diesel, are seeing their prices surge even more.
-
Growth (in the US) has remained resilient – GDP has expanded 1.5-2% this year and employment is strong, despite the higher rate environment. And, in fact, estimates have current growth even stronger for the latest quarter. Most investors have assumed we’re in restrictive territory, with an expected neutral interest rate of 3% – the level at which interest rates are neither positive nor negative for growth. This has called into question how restrictive current US interest rates actually are, and if in fact the neutral rate is higher than 3%. If so, rates and therefore bond yields would need to go higher to prevent the US economy from overheating.
- Government budget deficits have come back into focus as bond yields have risen. From Japan to Europe to the US, government deficits have been on the rise. Every new crisis we face brings with it another bout of government support, which seems to retain its place in budgets even when things get better. People still reeling from a cost-of-living crisis sparked by COVID and the Ukraine war are in no mood for government spending cuts. While inflation has returned to more normalised levels, wages haven’t kept pace, and now costs at the pump and utility bills are soaring once again. Also, the fact that the US debt pile has moved north of $40 trillion this year has dragged government spending back into the spotlight.
- The bond investor base is changing, and governments are having to tap increasingly sceptical bond markets for funds. These dynamics aren’t helped by the fact their traditional buyer base is dwindling – Japanese investors once flocked to the US treasury market to find low-risk attractive yields versus their domestic market. They were encouraged to do so by their own Japanese 10-year bonds averaging below 1% since the Global Financial Crisis. Today they offer 3.1%, providing genuine competition for capital just at a time the US needs its biggest supporter. On top of that, hyperscalers (Amazon, Alphabet, Oracle, Meta) have been issuing bonds hand over fist (about $80 billion so far this year, which is already 80% of last year’s total), and soaking up capital for high-quality bonds.
Winter is coming
All this points to a potentially poisonous mix for government bonds, with the risk that yields go yet higher. However, I think the oil price is the key protagonist in all of this. A calming of the situation in the Persian Gulf and an $80 oil price should immediately ease inflation concerns.
It wouldn’t solve everything, but it would help bring down bond yields (as we saw in May and June). That would take the pressure off government financing – the cost of interest is a significant part of their current deficits. And US economic growth should remain in good shape, too, as cheaper energy typically boosts GDP. Outside of energy, there’s little evidence of a genuine inflation issue.
If there’s no deal/fudge with Iran, and oil shortages continue as we head into winter, the inflationary impact will start to be felt, and central banks may be forced to act further. The US Federal Reserve already felt it had to act in last week’s meeting, hiking by a quarter-percentage-point to the 3.75-4.00% range. While American growth has been resilient, a lot of current activity can be traced back to the huge sums being spent building out data centres. Given it’s something of an arms race, this investment has so far been immune to the level of interest rates. This may continue, but the pressure on lower-income households and the housing market would certainly weigh on the economy, and if the equity market suffers, this could impact the spending of wealthier households in the US.
Support from the government in the form of the One Big Beautiful Bill has put more money in consumer pockets and encouraged companies to invest in the economy with big tax breaks. These two factors are arguably supporting what would otherwise be a much weaker economy. These factors, ironically, are headwinds to rate cuts. If that government support is to continue on top of the AI investment tailwind, then perhaps the Fed does in fact need to go higher from here. Certainly the market is now broadly expecting more rate hikes. But I would argue that does not necessarily mean the long-term neutral rate is higher. These are shorter-term forces, and the medium-term impact of AI is likely deflationary, reducing the need for higher rates.
Forage carefully
When building multi-asset portfolios, government bonds still play an important role. If growth stalls, they will likely rise in value, and act as a safe-haven again – especially the US, as it’s historically the world’s harbour in a storm. Inflation falling for good reasons (Iran agreement), or bad (slower growth), would also be supportive.
But the oil price staying higher and lighting a fire under inflation is the key risk. It would compel central banks to keep hiking, while pressuring government balance sheets at the same time. That would be nasty for bondholders.
This government spending problem didn’t happen overnight, so over the last couple of years we’ve diversified our government bond portfolio, balancing where we can find attractive yields with government balance sheet considerations. Earlier this year we reduced the duration of our portfolios – keeping our government bond exposure, but owning shorter-dated bonds – which still give attractive yields (roughly 4.8% on both the US and UK 5-year benchmark bonds). This should provide some protection to portfolios should growth falter. But they should be less impacted than longer-dated government bonds from fears around government largesse.
We also use diversifiers such as structured products linked to rate volatility to protect against inflation shocks, and put options to help cushion any impact on equities. It’s a good time to have more tools at your disposal.
Right now, a lot hinges on Iran. Whether it’s government budgets, central bank policy, picking government bonds, or foraging for mushrooms, there’s not much room for error.
For more information on the Rathbone Multi-Asset Portfolios, click here.