  • Wealth Management
  • Asset Management
  • Wealth Management
  • Asset Management
Location
  • United Kingdom
    Language
  • Jersey
    Language
  • Guernsey
    Language
  • US
    Language
  • MyRathbones login
  • Financial Planning login
  • Donor Advised Fund login
Home
  • Who we help
    Who we help

    We help a wide range of clients invest well so that they can focus on what matters.

    Who we help
    • Individuals and families

      Focusing on you and your individual goals.

    • Entrepreneurs and business owners

      Helping turn the success of your business into financial security for your family.

    • Financial advisers

      Working with you, for your clients.

    • Charities

      Helping charities invest in line with their mission and values.

    • Professional partners

      We work with lawyers, accountants and other professionals.

  • Our services
    Services

    See our wide range of services tailored for your needs.

    Our services
    • Investment Management

      Looking for someone to create an investment portfolio for you?

    • Wealth Management

      Our combined investment and planning service for a holistic approach to your finances.

    • Financial Planning

      Need help reorganising your finances and planning for the future?

    • Tax, trust and legal services

      Structure your wealth for the future by bringing together legal, tax, family, and investment considerations.

    • Greenbank Sustainable Investing

      Looking for investments that align with your values? See our sustainable investment options.

    • Personal Injury and Court of Protection

      Rathbones’ dedicated personal injury (PI) and Court of Protection (COP) team.

    • Private Office

      Helping clients with £5m or more to protect, grow and structure their wealth for the long term.

    • Private Banking with Investec

      Private, corporate, and investment banking services through our partnership with Investec bank.

  • About us
    About us

    A leading UK wealth manager with roots dating back to 1742.

    About us
    • Careers

      Learn more about what it’s like to work at Rathbones, and search our current vacancies.

    • Corporate governance

      Learn more about our Board, Executive Committee and our approach to corporate governance.

    • Investor relations

      Find the Rathbones Group Plc financials, reports, investment case and key events.

    • Media centre

      Read the latest news from Rathbones Group.

    • MyRathbones – Our digital platform

      Our secure online portal and app, designed to give clients a clear view of their investments with us.

    • Our purpose

      Our driving purpose is to help more people invest well, so they can live well.

    • Responsible business

      We believe in doing the right thing for our clients and for others too.

    • Awards

      Our awards and industry recognition reflects our commitment to exceptional wealth management.

  • Insights
    Insights

    Read the latest news and market commentary from our specialists.

    Insights
    • Financial planning

      Explore a range of topics affecting your finances, from retirement planning to the latest legislative changes.

    • Investing

      Read about the key investment themes affecting global markets.

    • Podcasts

      Listen in to or watch our specialists in one of our podcasts.

    • Responsible investing

      Explore our articles, reports and events on investing responsibly.

    • Webinars

      Timely insights, real conversations. Watch live or catch up anytime.

  • Contacts
    Contacts

    Whether you have a question about our services, or need to talk someone specific, we can help.

    Contacts
    • Our offices

      Find your local Rathbones office. We have 21 across the UK and Channel Islands.

    • Our people

      Find the contact details for your Rathbones team by searching our people’s directory.

    • Let's talk

      Our team will be in touch to help you book a no obligation consultation with an adviser.

    • Our media contacts

      Access the contact details for our media team.

    • Other contacts

      Need to contact us about something else? Here you'll find all the options.

Let's talk

SearchStax standalone input

Building prosperity: The growth test

26 October 2026

Are tax and economic policies helping or hindering investment, entrepreneurship and long-term prosperity? We share five recommendations to help the UK save, invest, and live well


  1. Home
  2. Knowledge and Insight
  3. Building prosperity 2026 report

Article last updated 26 October 2026.

Foreword

Turning ambition into investment-led growth

The UK approaches this Budget with a new government and a new Chancellor in John Healey but a familiar challenge: how to strengthen the public finances without further weakening the investment and enterprise on which sustainable growth depends.

Across the country, our clients are building businesses, creating jobs, investing for the future and supporting their families and communities. Yet many tell us that repeated policy change, rising costs and uncertainty are making long-term decisions harder.

Stability matters, but stability alone is not enough: the UK also needs a clear, credible programme to unlock productive investment and reward aspiration.

This report – detailed below or available as a PDF download – applies a simple growth test to the choices facing the Chancellor. Will they increase the pool of long-term savings available to British businesses? Will they improve the incentive to invest, scale and list in the UK? Will they help people and capital move to where they can be most productive? And will they give regions the capacity to turn greater autonomy into stronger local economies?

Our recommendations are practical. They recognise the difficult trade-offs facing any government, but also the cost of continuing with a tax and regulatory system that too often discourages saving, investment and mobility. The central message is clear: the route to stronger public finances and higher living standards runs through investment-led growth. This is particularly true of the Prime Minister’s drive for devolution – without meaningful regional investment there is no reason to believe decentralising the state will drive growth.

Rathbones has long-term relationships with people and businesses – entrepreneurs, professionals and SME owners – across our 21 regional offices in the UK. We see both the ambition that exists and the barriers holding it back. By giving that experience a voice, supported by our economic analysis, we hope to contribute constructively to the choices ahead and to a policy environment in which more people can invest well, live well and help build the country’s prosperity.

Download a copy of the report

A photo of Camilla Stowell

Camilla Stowell
CEO Wealth, Rathbones

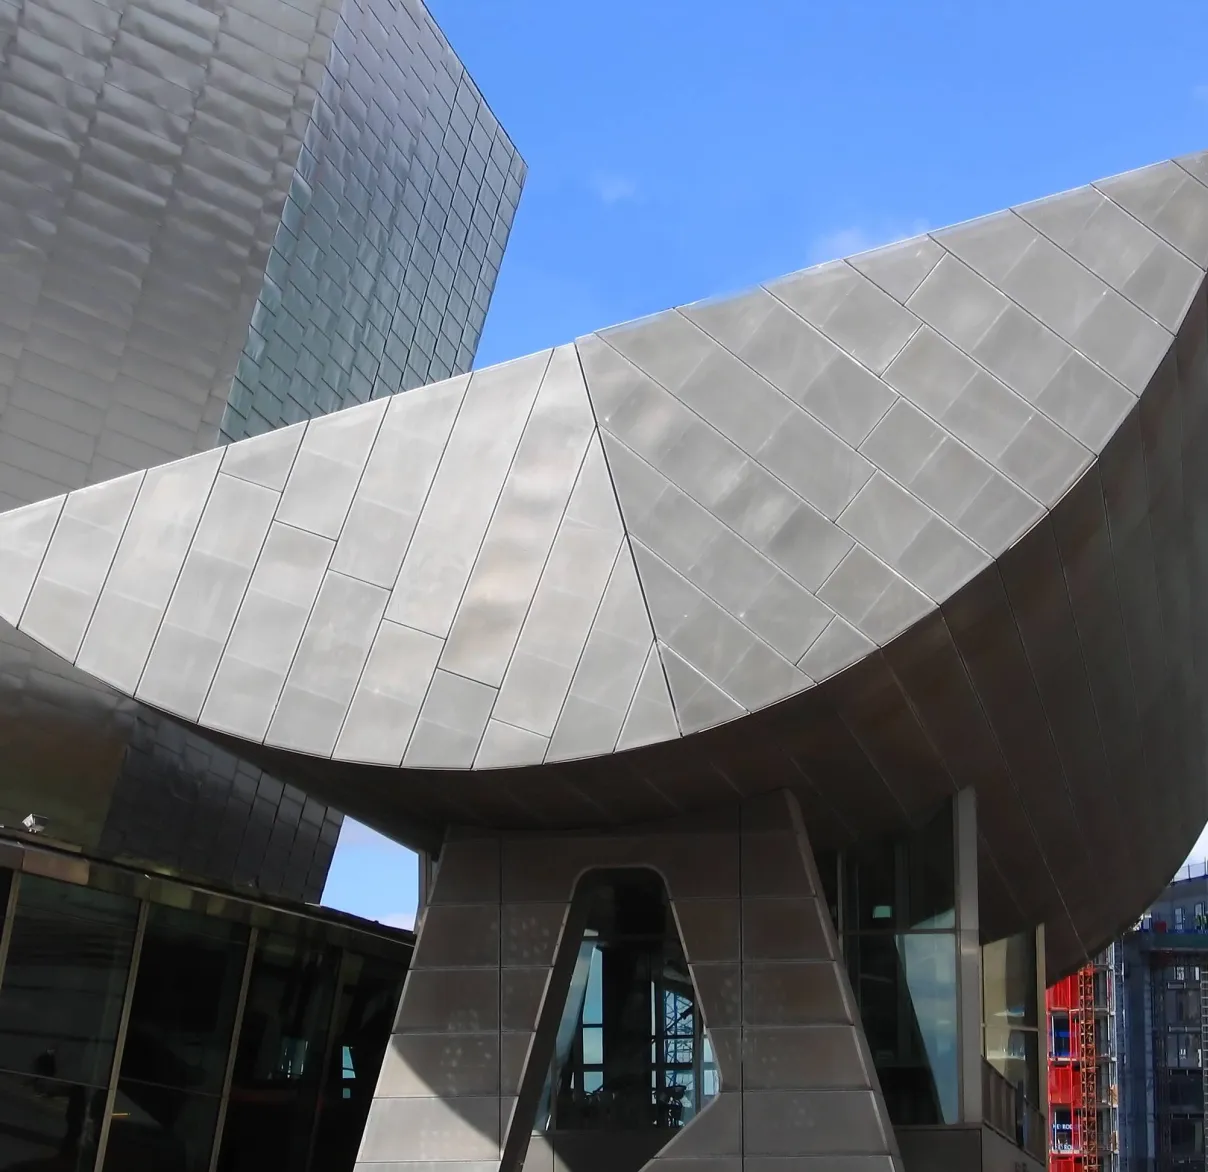
Our report's cover image shows The Lowry Arts Centre at Salford Quays, Greater Manchester, a place of regeneration from a declining docklands into a thriving cultural and economic hub.

Executive summary

Apply a growth test to the Budget

The Chancellor faces a difficult fiscal backdrop, with higher borrowing costs eroding room for manoeuvre. But tax rises that weaken saving, investment or mobility risk reinforcing the cycle of low growth and pressure on the public finances.

The durable answer is to increase productive investment and the economy’s capacity to grow. In this second edition of Building prosperity (access the 2025 edition), our evidence-led view from the front line of entrepreneurship and enterprise, we focus on five areas where practical reform can support sustainable growth across the country.

Protect incentives to save and mobilise more long-term capital for UK scale-ups

Pensions, savings and productive investment

Avoid further restrictions on pension tax relief or the tax-free lump sum, and investigate abolishing Stamp Duty Reserve Tax so UK equities are not placed at a structural disadvantage.

Jump to this section

Give firms the confidence and incentives to invest

Business taxation and competitiveness

Reform business rates so improvements are not penalised, maintain a stable corporation tax regime, and extend more generous capital allowances to buildings and intangible assets. Drive forward further planning reform and remove unnecessary regulation that discourages investment.

Jump to this section

Reduce barriers to moving home and relocating for work

Property taxation

Begin a credible programme to reform or replace Stamp Duty Land Tax, improving use of the existing housing stock, labour mobility and construction activity.

Jump to this section

Resist measures that drive capital away or discourage investment

Wealth taxes

Reject an annual wealth tax and approach any rise in capital gains tax with caution; if rates increase, reform the tax base to account for inflation and improve the treatment of investment losses.

Jump to this section

Match greater local power with investment and institutional capacity

Devolution

Treat increased local power as part of a wider growth programme that will not deliver growth unless it is seen as just one aspect of national prosperity.

Jump to this section

These proposals are not a complete policy platform, but a set of practical changes that, based on what we see and hear from business people around the UK, would make the country a more attractive place to save, invest, build and grow.

Together, they could help build prosperity in every region while strengthening the long-term outlook for living standards and the public finances.

Overview

Breaking the cycle of weak growth and rising taxes

On 28 October, new Chancellor John Healey faces the unenviable task of delivering his first Budget. But while the occupant of Number 11 has changed, the vicious cycle of tax hikes and weak growth appears set to continue.

Our view on how to break that cycle is clear: the UK needs to step up its pursuit of investment-led growth. That is the best way to put the public finances on a more sustainable path and raise living standards. This report sets out our recommendations.

A tighter fiscal backdrop

Since the Office for Budget Responsibility’s (OBR’s) latest forecast in March, the UK’s fiscal position has deteriorated as surging gilt yields have raised borrowing costs. This largely reflects conflict in the Middle East, with higher energy prices lifting expectations for inflation and interest rates. The benchmark 10-year gilt yield rose from around 4.5% when the previous forecast was made to about 5.4% by early October (figure 1).

In March, the OBR expected the government to meet its fiscal rule to balance day-to-day spending and revenue by 2029-30 with £24bn of ‘headroom’ – a margin for error. Recent estimates suggest roughly half of that buffer may have been eroded when the OBR runs the numbers again.

This is not necessarily an immediate problem. Rachel Reeves raised taxes at the last Budget partly to increase headroom and reduce the risk that future shocks would force course corrections. That decision has proved sensible given the impact of the Middle East conflict, although £24bn is not large by 2010s standards.

The Chancellor is therefore unlikely to need tax rises or spending cuts simply to meet the fiscal rules. But the rules are self-imposed and only rough guides to near-term sustainability; the long-run picture is more complex. Bond investors know this, so Healey may still need to err on the side of caution.

Like many advanced economies, the UK faces significant structural spending pressures. An ageing population is increasing demand for health and pensions, even after the tweak to the triple lock, while the working-age share of the population is shrinking. Geopolitical tensions require more spending on energy and food security and defence, and the end of ultra-low interest rates means higher debt-servicing costs.

Figure 1: UK 10-year government bond yield (%, 2026)

This helps explain speculation about tax rises to rebuild the fiscal buffer and bolster credibility. But badly designed or timed increases can weaken growth and future revenues, potentially harming the overall fiscal position and prompting further rises – a vicious cycle.

The case for investment-led growth

Growth-enhancing reforms are the way to break that cycle. A larger economy means higher tax receipts, all else equal, reducing the need for higher tax rates or spending cuts. More investment is a prerequisite for faster growth: economists generally agree that persistently low investment helps explain the UK’s weak productivity growth over the past two decades.1 Productivity is the amount workers produce in a given period.

Low investment leaves UK workers with less capital – buildings, machines, software, data, training and research and development – to support efficient production than peers in other advanced economies. One recent paper estimated that in 2019 each UK worker had about a third less capital than the average worker in the US, Germany, France and the Netherlands (figure 2).2

The Chancellor must therefore prioritise investment-led growth at this Budget and for the rest of his term. We made the same argument before Rachel Reeves’ final Budget and repeat it before John Healey’s first. Our recommendations cover five broad areas:

  1. Pensions, savings and productive investment
  2. Business taxation and competitiveness
  3. Property taxation
  4. Wealth taxes
  5. Devolution

These recommendations are not a complete policy platform, and some involve trade-offs only elected officials can make. Certain measures may reduce near-term revenue and need to be balanced by tax or spending changes elsewhere. But, if implemented well as part of a fiscally neutral package – one that does not increase the deficit – they could materially improve the long-term outlook for the public finances and living standards.

Figure 2: Capital stock per employed person (2019, UK = 100)

The 2030 Prosperity Alliance, an apolitical coalition of UK businesses, economists and civic leaders, recently argued that “businesses should ask for structural reform, not just tactical tweaks” and remain consistent across Budgets.3 We agree and have produced this report with that principle in mind.

Recommendation 1 | Pensions, savings, and productive investment

Protect the incentives to save, channelling capital into high-potential firms

For the UK economy to grow at a faster pace, it is imperative that the country’s most ambitious, dynamic, and innovative firms, and those who lead them, reach their full potential. In turn, that means the government needs to ensure they have access to the financing required to do so.

There is substantial evidence that high-growth firms (sometimes also referred to as ‘scale-ups’) play an outsized role in driving economic growth, through both creating employment and driving up productivity.4 However, data also suggest that part of the reason UK productivity growth has slowed since the Global Financial Crisis is because these firms have not been as successful in supplanting incumbents as their predecessors.5 In other words, business dynamism has fallen. Resources are not being reallocated to more productive firms as quickly.

There are numerous potential reasons why the UK economy has become less dynamic, ranging from the level of interest rates, to the tax system, to regulation and competition policy. While there is certainly more the government can do in many of these areas to boost dynamism, in the short term we think it is critical that it does not take action that exacerbates the problem by further disincentivising saving into pensions and limiting access to external financing.

Closing the scale-up funding gap

To help drive their growth, scale-ups tend to be more reliant on external finance than the average small and medium-sized enterprise. A considerable share report that accessing this funding poses a challenge to their future growth.6 Traditional bank lending can be tricky given the uncertainty of cash flows and lack of tangible assets, meaning many rely on venture capital (VC) and debt funds, and growth equity investors.7

While the UK is the centre of the venture capital industry in Europe, total VC investment was almost 25% smaller than the US between 2023 and 2025, adjusted for the relative size of the economies.8 The difference is most pronounced at later stages. While the UK saw 9% of global VC investment at the startup stage in 2025 (the same as the Bay Area in the US), it accounts for only 6% at the breakout, and 5% at late stage (where the Bay Area accounts for 16% and 48% respectively – figure 3).9 Innovative businesses struggle to scale in the UK.

Pensions are well-placed to help. They are the biggest store of household savings in the UK, accounting for 54% of total wealth.10 And their long investment horizons mean they can be patient, as is generally required for private investments. There is evidence from across 34 OECD countries that increased pension saving is associated with stronger growth of firms that are more reliant on external finance.11

However, while 72% of US venture capital money comes from pension funds, they make up just 10% of the VC pool in the UK.12 The lack of domestic capital appears more problematic as firms grow. Almost half of investment raised at the startup stage came from UK investors, but only a quarter did at late-stage.13 This helps to explain why the UK can’t retain its most exciting firms.

Figure 3: Share of global VC investment by region

The view from Manchester

Rathbones’ Manchester office reports growing weariness among business owners, with rising costs and economic uncertainty leaving more feeling under pressure and considering an earlier exit. Without sufficient access to long-term growth capital, there is a risk that promising UK businesses are sold earlier than planned, transferring ownership before their full value can be created and retained within the domestic economy. This presents an opportunity to channel capital towards high-growth businesses, but also highlights the risk that difficult operating conditions prompt founders to sell before their companies reach their full potential.

To the government’s credit, it has been taking steps to improve the situation. In the 2025 Mansion House Accord, major defined contribution (DC) providers pledged to invest 5% of assets in UK private markets. The Pension Schemes Act 2026 gives the government some powers to mandate this. The Act also includes measures to consolidate DC pension schemes, giving them in theory the economies of scale to invest more in private assets, ensuring investments align with the schemes’ fiduciary duties.

In this context, recent changes affecting the incentives to put money into pensions are incongruous. In 2024, the government announced that pensions would no longer be exempt from inheritance tax from 2027. In 2025, it announced that only the first £2,000 of employee pension contributions through salary sacrifice would be exempt from National Insurance.

John Healey should resist the temptation to make it a hat-trick in 2026. The government should steer clear of changes that further disincetivise pension saving, such as reducing income tax relief on contributions or cutting the tax-free lump sum. Our conversations with clients suggest that doing so would almost certainly lead to people reducing how much they save in their pension pots – an unwelcome headwind to efforts to help the UK’s most innovative firms scale.

There is also a strong argument against such changes on the grounds of pensions adequacy. The government’s own statistics show that 45% of working-age adults currently save nothing into a pension, while retired people in 2050 are on track to have 8% less private pension income than those today.14 Tightening the tax treatment of pensions today may only mean storing up more problems tomorrow.

10% vs 72%

The difference in venture capital money from pension funds in the UK vs US.

"The government’s own statistics show that 45% of working-age adults currently save nothing into a pension, while retired people in 2050 are on track to have 8% less private pension income than those today."
"The government knows that SDRT is damaging the incentive to list in the UK. After all, it felt the need to introduce a three-year relief for newly listed shares at the 2025 Budget."

Recommendation 2 | Business taxation and competitiveness

Reward investment and give businesses the confidence to grow

Ensuring an adequate supply of savings to support investment is one side of the equation. But firms need to want to invest, too. Andy Burnham has stated that he wants to give people “the confidence that if they have a great idea, they’ll get all the support they need to bring it to life.” The Chancellor has told his fellow G20 finance ministers that Britain is “a country whose people, and businesses and communities are ready to seize the opportunity of new technologies and new ideas.”

If the government is as serious about supporting investment and innovation as it claims to be, we think it should be focusing its efforts on a few key areas: business rates, capital allowances, and regulation.

Reforming taxes that penalise investment…

Business rates have already been in the spotlight since Burnham took office in July. Indeed, in the Prime Minister’s first week, the government announced a cut to business rates for pubs, clubs, and live music venues in England from April 2027. This will be funded by a review of reliefs for firms that don’t make a “positive contribution” to local communities, such as vape shops.

While this cut is presumably popular with parts of the electorate and will be a helping hand to some businesses in the sector, it also introduces even more complexity to what is already a maze of reliefs and exemptions. And perhaps most importantly, we think it distracts from a more fundamental issue with the current business rates system.

The problem stems from the fact that business rates are levied on the estimated rental value of a property. If a business invests in improvements to its premises, increasing its rental value, then its tax burden rises too. That’s a clear disincentive to undertake upgrades to commercial property. In fact, a recent Confederation of British Industry survey of almost 700 firms found that nearly a third had cancelled, reduced, or delayed investment in their properties at least in part because of business rates.19

Labour highlighted this in its 2024 manifesto – the same place it committed to replacing the current system in England.20 But since winning power, it has pursued piecemeal changes rather than wholesale reform.

We think bolder action is needed. In the near term, this could be making improvement relief more generous. Eventually, the government should be aiming for a system where only the land under commercial property is taxed, not the buildings atop it. This would be much more desirable from an economic perspective.

…and changing the design of others to encourage it

Moving on, capital allowances are a much less politically salient topic than business rates, but changes to them could also improve the UK’s growth prospects. That’s because they incentivise investments by allowing firms to deduct the cost of them from profits before paying tax.

The UK has made some laudable progress on this front in recent years. Some more generous temporary capital allowances introduced in the wake of the pandemic were converted into permanent measures by the Conservative government in 2023, such as allowing certain plant and machinery investments to be fully expensed.

The Starmer government then committed to maintaining that system for the duration of the current parliament. However, tweaks made by Rachel Reeves at the 2025 Budget were unhelpful. She reduced the generosity of capital allowances in net terms via a reduction in the writing down allowance, only partly offset by a new first-year lease allowance.

Even so, recent Tax Foundation analysis calculates that, on average, businesses can currently recover 72% of capital investment costs, up from 57% in 2019. That takes the UK from the fourth worst of 36 OECD members back then to just inside the top half today (figure 4).21

We think Healey should continue down this path by recommitting to the current regime, maintaining current rates of corporation tax on all sectors (including banks), and looking at improving it further. One way to do so would be to enhance tax incentives for other types of business investment where they are still limited by international standards, such as for buildings and intangibles (non-physical assets such as software and research & development).

This would make the UK more competitive by international standards when firms are deciding where is best to invest. It would also remove the bias in the tax system for certain types of investment over others, allowing firms to make decisions based solely on what is most efficient. This is particularly important given that, for many of the service and knowledge-based industries that make up much of the modern UK economy and the emerging AI economy, buildings and intangible assets account for a substantial share of their investment.

Figure 4: Weighted average capital allowance in OECD countries

1/3

of businesses have cancelled, reduced or delayed property investment in part because of business rates.

"If a business invests in improvements to their premises, increasing its rental value, then their tax burden rises too."
£30,000

has been added to the cost of building a home by regulation since 2020.

Building a more competitive business environment

Finally, there is also plenty the government can do away from the tax system, such as in regulation, and particularly planning. The complex environment in the UK makes building anything very expensive and time-consuming. The burden also gives established firms an advantage over innovative challengers, given the resources needed to comply.

The Lower Thames Crossing tunnel is a perfect example. By the end of 2022, the planning application alone had cost more than a quarter of a billion pounds.22 That’s almost twice as much as Norway spent on a road tunnel completed in 2000 that is more than six times the length.23 Elsewhere, the Home Builders Federation estimates that regulation alone has added more than £30,000 to the cost of building a new home since 2020.24 Another estimate finds that the cost of compiling a planning application for a greenfield development of 40 new homes has increased 3.6 times since 1990, adjusted for inflation.25

The Starmer government made some progress on this front with the Planning and Infrastructure Act. Since this Act became law less than a year ago, it is too early to draw conclusions on how effective it will be. However, the Burnham government should take up the mantle and go faster and further to reform planning and review existing legislation in other areas to decide whether it is fit for purpose. Rules that have been created incrementally, which may make sense in isolation, can end up doing more harm than good when assessed cumulatively.

Recommendation 3 | Property taxation

Reform transaction taxes to unlock housing mobility, labour mobility and growth

Historical underinvestment in the UK isn’t limited to businesses. Investment in dwellings has been at or around the lowest in the G7 relative to GDP since at least 1985. The cumulative effect of this is the housing shortage the country finds itself in. Economic growth requires workers, yet we have failed to build sufficient homes in which they can live.

According to OECD data, England has 441 homes per 1,000 people. In Germany, there are 518 homes per 1,000 residents. In Spain, it’s 563. In France and Italy, the number is close to 600 (figure 5).26 Furthermore, the proportion of vacant houses is the second lowest of the twelve countries for which data is available, above only the Netherlands.

Making better use of Britain’s housing stock

However, the shortage of supply is only part of the story. The UK is also inefficient in how it utilises its homes. The 2024-25 English housing survey found that 40% of properties are under-occupied (defined as having two or more bedrooms than required).27 Understandably, under-occupation is more common for the over-65s. Among those households, 58% are under-occupying, up from 53% ten years earlier – an increase of almost one million households.

For many, this is simply a lifestyle choice. However, plenty appear to be open to downsizing. Several polls over the past decade or so suggest that between a quarter and a half of older households are interested in the idea. And from an economic standpoint, it is sensible to make doing so as easy as possible.

Downsizing increases the supply of homes for younger, growing families to move into. On top of potentially improving the quality of day-to-day life for households on both sides of a transaction, it also allows working-age individuals to relocate more freely. This makes it easier for workers to find jobs where they are more productive. It also helps firms fill staff and skill gaps that are preventing them from growing. In other words, it improves labour mobility.

Figure 5: Dwellings per 1,000 inhabitants (2022 or latest)

Yet, by levying Stamp Duty Land Tax (SDLT) on property purchases, the government is actively disincentivising both downsizing and broader labour mobility. A July 2026 poll by Public First, a public policy research consultancy, found that almost a quarter of people cite it as one of the main barriers to moving house. This rises to over a third for those aged 55–64 (figure 6).28 Almost half of downsizers or would-be downsizers said it affected their decision-making, while 17% of people who seriously considered moving for work but decided against it named SDLT as a key factor.

This is why former IFS Director Paul Johnson repeatedly called SDLT “among the most economically damaging of all our taxes”.29 It’s also why signatories from nine think-tanks reaching across the political spectrum agreed that the abolition of SDLT was a key tax reform for encouraging growth.30 And it’s why the cross-party House of Commons Housing, Communities and Local Government (HCLG) Committee concluded in June this year that SDLT “must not be maintained in its current form and needs to be reformed”.31

Burnham is also a longstanding critic of SDLT. Back in 2010 he called it “a tax on the aspirations of young people to put down roots and get on in life” and proposed scrapping it and generating the revenue from a recurring tax on land values instead.32 However, after taking office in July, Burnham ruled out pursuing such a change in this Budget.

To be fair to the Prime Minister, three months is a very short turnaround to plan such a radical reform that would require a very careful transition. And the near-term clarity he’s provided, by ruling out change for now, will prevent speculation delaying transactions in the housing market.

Nonetheless, we strongly encourage his government to pursue longer-term reforms to property taxation that would reduce or eliminate the distortions caused by SDLT. The sooner the better – we think it would be wise to heed the recommendation of the HCLG Committee to begin looking at reform options before the end of this year. Ensuring the existing housing stock is used more efficiently can ease pressure on the housing shortage while the UK begins to make up for decades of underbuilding.

Figure 6: Respondents saying SDLT is a top three barrier to moving home, by age

Public First estimates that abolishing SDLT on primary residences could increase transactions by 16% and increase housebuilding by almost 11,000 homes per year, boosting GDP by around 0.2% even before accounting for the longer-run benefits in productivity from increased workforce mobility. What’s more, while the abolition would reduce tax revenue unless combined with tax rises elsewhere, it’s notable that modelling suggests around 25% of the cost would be offset by higher tax receipts associated with more transactions and construction activity.

Beyond SDLT, we think the government should refrain from trying to raise more money from the high value council tax surcharge (better known as the mansion tax) announced in the 2025 Budget. At best, it is a sticking plaster for an outdated council tax system that raises a trivial sum of money. And more broadly, making changes to a tax that has not even been introduced yet would not be emblematic of the stability the Prime Minister has pledged to restore.

11,000

more homes a year could be built if SDLT was abolished on primary residences.

Find out more

Property investment is not the golden goose it once was. Read more in Rathbones’ report Don’t bet the house: why the golden age of property is over. 

Open the report

Recommendation 4 | Wealth taxes

Resist taxes that discourage investment and weaken entrepreneurship

Last month, John Healey said he wants to see the UK as a “country of wealth creation”. In August, Burnham told the Financial Times that “we need wealth creation and the best wealth creators not just forging their path here, but staying here.” If those statements are sincere, they should ignore repeated calls to impose an annual wealth tax.

Ahead of the 2025 Budget, 53 MPs (including 26 Labour MPs and several former Labour MPs sitting as independents) signed a motion proposing a 2% annual wealth tax on individual assets over £10m. That same proposal is resurfacing ahead of this year’s Budget. The Compass thinktank, which has links to the Prime Minister, recently published policy proposals for the new administration, including that same 2% annual wealth tax on assets over £10m.33 Other organisations, such as campaign group Tax Justice UK, continue to back it, too.

While he has avoided publicly backing a wealth tax himself, Burnham said in a speech to Compass last year that “we have overtaxed labour and undertaxed wealth.” And when asked about the prospect of a wealth tax by Gary Lineker, the broadcaster, in an interview just before taking office, Burnham didn’t rule the idea out.

Consequently, it is worth restating the arguments we have made before for why imposing an annual wealth tax is a bad idea for a government looking to boost investment and growth. You can find out more in our 2025 report on the idea of a wealth tax. 

The rise of the internationally mobile

Rathbones research shows that nearly 6,000 business owners left the UK between January 2024 and January 2026, almost twice the number who arrived; software was among the sectors to see the greatest number of departures.

The trend matters because when entrepreneurs relocate, the UK risks losing not just personal wealth, but investment, expertise, jobs and future growth. Rathbones also found that the number of active UK high-growth companies with an international founder fell in 2024 for the first time in more than a decade.

Tax stability, a competitive business environment and access to scale-up funding are therefore essential to keeping globally mobile founders, capital and economic activity in the UK.

The hidden costs of an annual wealth tax

First, compliance would be expensive. Regular valuations for a huge range of assets would be required, many of which would have no clear market price. In 2020, the independent Wealth Tax Commission estimated that a wealth tax on assets above £10m (at a rate of 1.12%, to raise £10bn per year) would mean over £700m in annual administrative costs for those paying it.34 That would make compliance almost twice as expensive as VAT relative to the revenue raised – and VAT itself has a relatively high administrative burden.35

Second, there can be significant unintended consequences for those with wealth in illiquid assets, such as private businesses. Studies from Norway and elsewhere find that private business owners facing wealth taxes pay much higher dividends to meet tax bills. The knock-on effect of this is their businesses investing less and growing less.36 This is a key reason why most countries, including the UK, tax wealth transfers via capital gains and inheritance taxes.

Third, wealth taxes can create significant economic distortions. They can encourage wealthy individuals to move money into less productive assets that might be exempt from the tax, or outside the UK altogether. There is a large range of estimates for the potential magnitude of this effect, but in the most detailed study of a possible UK wealth tax, the authors argued a 1% rate would shrink the taxable base of assets by 7–17%.37 That’s equivalent to at least £100bn shifting into less productive assets or leaving the UK. A 2% rate could have an even larger impact.

We think this host of issues makes the imposition of an annual wealth tax unlikely in this Budget. However, given Burnham’s political stance and manifesto commitments not to increase the rates of income tax, National Insurance, or VAT, it is more plausible that the government could raise other taxes on wealth. One recent area of speculation has been the possibility of an increase in the rates of capital gains tax (CGT). Influential cabinet members Louise Haigh and Wes Streeting have both proposed such a change in the past year.38

"Rathbones research shows that nearly 6,000 business owners left the UK between January 2024 and January 2026, almost twice the number who arrived."
£2bn

The reduction in tax take if the higher rate of CGT was increased by 10 percentage points.

Consider changes to CGT with caution

The government should tread very carefully here. For one, the revenue raised from increases in CGT rates can disappoint relative to what advocates of the policy claim because people can adjust their behaviour to try and reduce their tax bill. This could be selling in anticipation of a hike, holding assets for longer than would otherwise be the case in the hope rates will be cut again, or leaving the UK entirely.

This has happened historically (figure 7), and is why HMRC’s own estimates of the revenue impact of CGT hikes are often negative. Increasing the higher rate by 10 percentage points, for example, is expected to reduce the tax take in 2027-28 by more than £2bn.39

Ministers should also carefully consider the impact any change to capital gains tax might have on levels of investment, given the importance of driving UK economic growth. With another summer of political upheaval, a fresh external shock from the conflict in the Middle East, and longer-term interest rates surging over the past few months, there are already significant headwinds to investment. A CGT hike could send a signal that only adds to the problem.

If the government decides it is set on raising the rates of CGT to align with income tax, then it is crucial that it does so alongside broader reforms to the tax base (what the tax rate is applied to). Existing issues with the CGT base would only be exacerbated by higher tax rates, so any hike needs to be accompanied by reforms. There are two key ones that would be necessary.

The first is to introduce a more sensible tax-free allowance.40,41 At present, the entire nominal gain made on an investment is subject to CGT, ignoring the impact of inflation. Consider a case where an asset’s value rises in line with inflation (meaning the proceeds from a sale cannot be used to purchase more goods and services than the money used to acquire it). An investor still pays tax on the gain despite being no better off in ‘real’ terms. Reintroducing a tax-free allowance for gains up to inflation would correct this (the UK had this allowance between 1987 and 1998).

A potentially superior option would be to only tax gains above the ‘risk-free rate’ (the interest rate available from holding a ‘safe’ asset such as cash or government bonds). There are a few ways to do this, but the key point is that the risk-free rate reflects the ‘time value of money’ (the compensation required purely for the delay in having money available) and so should not be taxed. Either of these changes to tax-free allowances should generally offset some of the impact of higher marginal CGT rates on the effective CGT rate and improve investment incentives.

Figure 7: Capital gains tax receipts around tax changes (% of GDP)

The second key reform would be to improve the tax treatment of investment losses.42 Current restrictions on using losses to offset gains elsewhere or income mean there is an asymmetry: government shares in all the upside from successful investments, but not in the downside from unsuccessful ones. While there are administrative challenges to preventing abuse, the government should investigate where reforms are feasible to try and level the playing field and encourage more investment, entrepreneurship, and economic growth.

Recommendation 5 | Devolution

Devolve with purpose: pair local power with investment and clear accountability

Finally, it would be remiss to comment on the Burnham government’s plans without talking about devolution – the transfer of powers from central government to local and combined authorities – which is clearly at the heart of the Prime Minister’s policy agenda. While we think there are plenty of good reasons to pursue devolution in some form, we caution against relying on it as a silver bullet for the UK’s economic woes. It should be a complement to the recommendations made above, not a substitute.

The potential benefits of local decision-making

One simple reason to devolve more powers to a local level is that voters want it. Polling suggests solid support for more devolved powers in areas where there are metro mayors.43 This should come as little surprise given that government in the UK is very centralised by international standards. In 2024, almost 92% of UK tax revenue was collected by central government. Meanwhile, 79% of spending was done by Westminster. That makes the UK one of the most fiscally centralised major advanced economies (figure 8).

It is possible that devolution, if executed well, could be positive for economic growth. For example, in certain policy areas such as transport or skills, local decision makers may be better placed to know what is best for growth in their area than those in Whitehall. Local government may also be able to co-ordinate across policy areas better than central government, in part because they are smaller, making cross-department communication potentially easier.

Additionally, reforms to funding models could provide more stability and facilitate better long-term planning. Councils and combined authorities currently rely heavily on central government grants, which can be short-term, uncertain, and tied to competitive bidding processes.

Experimentation is another possible benefit. Innovation isn’t limited to the private sector. If local governments are given sufficient freedom to pursue different policies, that will provide plenty of opportunities for ‘natural experiments’ to draw stronger conclusions on what works, and what doesn’t.

Figure 8: Central government tax revenue and expenditure as a share of total (2024, %)

Why devolution cannot deliver growth alone

However, devolution will almost certainly not be a panacea for sluggish economic growth in the areas it is pursued in. Although there is some evidence from single-country studies that it supports growth, cross-country analyses produce more mixed results, partly because it is difficult to separate the effect of devolution from wider institutional and political factors.44 The benefits of fiscal decentralisation appear to depend heavily on design.

A simple look at the data for advanced economies demonstrates that point. There is no clear relationship between the degree of fiscal centralisation and the level of GDP per capita (figure 9). At best, there are too many other moving parts for fiscal devolution to explain differences in productivity by itself.

Evidence suggests growth outcomes are stronger when fiscal powers are combined with administrative and political devolution, because that gives local leaders the authority and the accountability to act.45 Governance quality is also critical: decentralisation can support regional convergence where institutions are already strong, but it may widen disparities where they are weak. The clearest growth effects appear when local governments gain responsibility for public investment, which can attract additional private investment through a ‘crowding-in’ effect.

Indeed, while Burnham’s home turf of Greater Manchester is often cited as an example of successful devolution, its experience also illustrates the importance of pre-existing institutional capacity, strategic continuity, and a credible pipeline of investment. Greater Manchester’s development also rests on foundations laid before Burnham became its first mayor in 2017.

Under Sir Richard Leese and Sir Howard Bernstein’s leadership of Manchester City Council from the late 1990s, the city pursued a long-term redevelopment strategy that arguably laid the foundations for the relatively strong growth it has achieved over the past decade. Sir Howard helped lead the redesign and rebuilding of Manchester city centre, revive its commercial and retail core, promote cooperation across ten local authorities, support the successful delivery of the 2002 Commonwealth Games, and champion major infrastructure and cultural projects.

Fiscal centralisation and GDP per capita (2024)

Accordingly, devolution could even exacerbate existing economic inequalities in the UK if better-resourced regions are able to use new powers more effectively than weaker ones. And in any case, it’s unlikely that those inequalities are solely the result of over-centralisation.
It seems likely that the UK’s particularly unequal economic geography has been shaped at least in part by deindustrialisation and the rise of a services-led economy concentrated in and around London.46 High-value tradable services, such as financial services and consulting, benefit strongly from agglomeration economies: firms and workers become more productive when they are clustered together. As the UK shifted from manufacturing towards services, productivity gaps between places became more likely to widen.

Allowing regional authorities to collect and spend a portion of tax revenue will not by itself close those productivity gaps. Devolution would need to be accompanied by meaningful investment, and it remains unclear where that investment would come from. If the private sector were willing to lead this investment unaided, it would likely already have done so. This brings us back to the recommendations we have already made, which should make investment a more attractive proposition across the country.

Undoubtedly, devolution can play a role in reversing the UK’s economic fortunes. But the devil will be in the detail, it will take time to bear any fruit, and most importantly, it should not be relied on to do the heavy lifting alone. It must be part of a more comprehensive package of reforms to deliver faster growth.

Endnotes

Sources and further reading

  1. Glass, Anthony J., Sam Williams, Madeleine Matos, Thomas Elder, and David Artnett. “The UK productivity puzzle: a survey of the literature and expert views.” International Journal of the Economics of Business 32, no. 1 (2024): 31–65. 
  2. Allas, Tella, and Dimitri Zenghelis. “The UK’s capital gap: a short-fall in the trillions of pounds that will take decades to bridge.” Productivity Insights Paper no. 055 (2025).
  3. Kakkad, Jeegar, and Shivani Menon. The Five Giants – Neglect. 2030 Prosperity Alliance, 2026.
  4. Hamilton, Robert T., and Poh Yen Ng. “What we know about high-growth firms, and what we do not: A systematic review.” International Small Business Journal: Researching Entrepreneurship 43, no. 4 (2025): 420–451.
  5. Davies, Richard, Nadim Hamdan, and Gregory Thwaites. Ready for Change. Resolution Foundation, 2023.
  6. ScaleUps Debt Finance Journey. ScaleUp Institute, 2023; Brandily, Paul, Mimosa Distefano, Krishan Shah, Gregory Thwaites, and Anna Valero. Beyond Boosterism. Resolution Foundation, 2023.
  7. “Who finances UK business?” Bank of England. https://www.bankofengland.co.uk/bank-insights/2026/who-finances-uk-business.
  8. Small Business Equity Tracker 2026. British Business Bank, 2026.
  9. “UK startups & VC landscape evidence pack.” GOV. UK. https://www.gov.uk/government/publications/letter-to-the-prime-minister-on-investment-in-innovative-science-and-technology-companies/uk-startups-vc-landscape-evidence-pack-html.
  10. Delestre, Isaac, and Laurence O’Brien. “How is wealth distributed across British households? Reassessing the valuation of pensions.” Institute for Fiscal Studies (2026).
  11. Bijlsma, Michiel, Johannes Bonekamp, Casper van Ewijk, and Ferry Haaijen. “Funded Pensions and Economic Growth.” De Economist 166 (2018): 337–362.
  12. “British Business Bank – written evidence.” House of Lords Communications and Digital Select Committee inquiry: Scaling Up: AI and creative tech. https://committees.parliament.uk/writtenevidence/131002/html/. 
  13. “UK startups & VC landscape evidence pack.” GOV.UK. https://www.gov.uk/government/publications/letter-to-the-prime-minister-on-investment-in-innovative-science-and-technology-companies/uk-startups-vc-landscape-evidence-pack-html.
  14. “Government revives landmark Pensions Commission to confront retirement crisis that risks tomorrow’s pensioners being poorer than today’s.” GOV.UK. https://www.gov.uk/government/news/government-revives-landmark-pensions-commission-to-confront-retirement-crisis-that-risks-tomorrows-pensioners-being-poorer-than-todays .
  15. “Financial Transactions Taxes Around the World” Center for Economic and Policy Research. https://cepr.net/publications/financialtransactions-taxes-around-the-world/.
  16. Investing in the UK. House of Commons Business and Trade Committee, 2026.
  17. Hawkins, Mike, and Julian McCrae. “Stamp duty on share transactions: is there a case for change?” Institute for Fiscal Studies (2002).
  18. Stamp duty on shares: analysis of its economic impact and the benefits of its abolition. Oxera, 2024.
  19. “Business rates system a major barrier to UK investment and competitiveness.” CBI. https://www.cbi.org.uk/media-centre/articles/business-rates-system-a-major-barrier-to-uk-investment-and-competitiveness/.
  20. Change. The Labour Party, 2024.
  21. “Capital Cost Recovery across the OECD, 2026 Update.” Tax Foundation. https://taxfoundation.org/data/all/global/capital-allowances-cost-recovery-2026/; “Capital Cost Recovery across the OECD, 2019.” Tax Foundation. https://taxfoundation.org/data/all/global/capital-cost-recovery-across-the-oecd-2019/.
  22. “Lower Thames Crossing application’s £267M cost highlights complexity of planning system.” New Civil Engineer. https://www.newcivilengineer.com/latest/lower-thames-crossing-applications-267m-cost-highlights-complexity-of-planning-system-06-12-2022/.
  23. “Revealed: How the Lower Thames Crossing is breaking records for all the wrong reasons.” Britain Remade. https://www.britainremade.co.uk/revealed_how_the_lower_thames_crossing_is_breaking_records_for_all_the_wrong_reasons.
  24. The Viability Crunch. Home Builders Federation, 2026.
  25. Wnek, Bertie. The Five Giants – Gridlock. 2030 Prosperity Alliance, 2026.
  26. “OECD Affordable Housing Database.” OECD. https://www.oecd.org/en/data/datasets/oecd-affordable-housing-database.html.
  27. “English Housing Survey 2024 to 2025: age cohorts.” GOV.UK. https://www.gov.uk/government/statistics/english-housing-survey-2024-to-2025-age-cohorts/english-housing-survey-2024-to-2025-age-cohorts.
  28. Zundel, Tom. “The economic benefits of Stamp Duty reform.” PF Global (2026). https://pf.global/insights/the-economic-benefits-of-stamp-duty-reform.
  29. “Autumn Budget 2024: initial IFS response.” Institute for Fiscal Studies. https://ifs.org.uk/articles/autumn-budget-2024-initial-ifs-response.
  30. Tax Reforms for Growth. CenTax, 2025.
  31. Affordability of Home Ownership. Housing, Communities, and Local Government Committee, 2026.
  32. “Land value tax – not old or New but true Labour.” The Guardian. https://www.theguardian.com/commentisfree/2010/aug/26/land-value-tax-labour-party.
  33. Ending Business as Usual: Policy Options for a Progressive Government. Compass, 2026.
  34. Advani, Arun, Emma Chamberlain, and Andy Summers. A wealth tax for the UK. Wealth Tax Commission, 2020.
  35. The administrative cost of the tax system. National Audit Office, 2025.
  36. Berzins, Janis, Øyvind Bøhren, and Bogdan Stacescu. “Shareholder illiquidity and firm behaviour: financial and real effects of the personal wealth tax in private firms.” European Corporate Governance Institute Finance Working Paper 646/2022 (2022); Ebeltoft, Jens Christian, and Nicolai Johnsen. “Liquidity effects of the Norwegian wealth tax”. (2022); Barroso, Raúl, Donald N’Gatta, and Gaizka Ormazabal. “Individual wealth taxes and corporate payouts.” The Accounting Review 98, no. 5 (2023): 31-60.
  37. Advani, Arun, and Hannah Tarrant. “Behavioural responses to a wealth tax.” Fiscal Studies 42, no. 3-4 (2021): 509-537.
  38. Louise Haigh. “Rebuilding the UK tax system: fairness, growth, and the renewal of the social contract.” Renewal 34 (2026); “Wes Streeting pledges ‘wealth tax that works’.” BBC News. https:// www.bbc.co.uk/news/articles/cm2pxz7de41o.
  39. “Direct effects of illustrative tax changes bulletin (June 2025).” GOV.UK. https://www.gov.uk/ government/statistics/direct-effects-of-illustrative-tax-changes/direct-effects-of-illustrative-tax-changes-bulletin-january-2025.
  40. Advani, Arun, Andrew Lonsdale, and Andy Summers. Reforming Capital Gains Tax: Revenue and Distributional Effects. CenTax, 2024; Adam, Stuart, Arun Advani, Helen Miller, and Andy Summers. Capital Gains Tax Reform. Institute for Fiscal Studies, 2024.
  41. Either of the changes to allowances mentioned below would need to be accompanied by similar changes to the tax treatment of interest on cash savings.
  42. Advani, Arun, Andrew Lonsdale, and Andy Summers. Reforming Capital Gains Tax: Revenue and Distributional Effects. CenTax, 2024.
  43. “Place over politics: What polling tells us about how successful devolution has been to date.” Centre for Cities. https://www.centreforcities.org/publication/place-over-politics/.
  44. Baskaran, Tushyanthan, Lars P. Feld, and Jan Schnellenbach. “Fiscal federalism, decentralization and economic growth: A meta-analysis.” Freiburger Diskussionspapiere zur Ordnungsökonomik no.16/02 (2016).
  45. Fiscal Decentralisation and Inclusive Growth. OECD, 2018.
  46. Brandily, Paul, Mimosa Distefano, Hélène Donnat, Henry G. Overman, and Krishan Shah. Bridging the Gap. Resolution Foundation, 2022.
Take a copy with you

This webpage contains all of the report's contents, but you can download a copy in a PDF format via the button. 

Download a PDF of this report

Take action

If you would like to talk to one of our team about the announcements in the Budget and how we could help you make a plan, please fill in the form below and we'll get in touch. Alternatively, please feel free to call us on 0330 390 9191 and we’d be happy to help.

A typical Rathbones client has over £300,000 to invest or plan their financial future, including pensions but excluding property. 

  • Current Your details
  • Your enquiry
  • How we handle data
I am a/an

If you need immediate assistance, please don't hesitate to call our Helpdesk at 0800 151 3355. We're available Monday to Friday, from 8am to 6pm (excluding bank holidays), and we're here to help with any questions or issues you may have.

If you're interested in registering for MyRathbones, please reach out to your investment manager directly or read more about the platform here.


If you are an existing client, please contact your investment manager or financial planner directly to address your query or visit ⁠our people page to find their details.


More Autumn Budget 2026 analysis

Professional business woman standing on phone infront of navy blocked wall

5 minutes

19 October 2026

Autumn Budget 2026: financial planning tips for partners and senior executives

The Autumn Budget will generate plenty of headlines. But for partners, senior executives, and other high earners, the most important questions are often more personal.
Autumn Budget 2026: financial planning tips for partners and senior executives
Woman looking at tablet with colleague

6 minutes

16 October 2026

Your next move shouldn’t depend on a Budget prediction

When you run your own business, your personal plans usually rise and fall with it. A Budget can change the detail. But knowing what you need from the business helps you understand whether your plans still add up and what, if anything, needs adjusting to keep them on track.
Your next move shouldn’t depend on a Budget prediction
Three people seated in a studio with dark blue décor, facing the camera during a filmed panel discussion.

55 mins

1 October 2026

Autumn Budget 2026: Preparing for change

A recorded webinar with insight into the changes that could shape your financial plans – from confirmed tax rises to the speculation dominating the headlines.

Autumn Budget 2026: Preparing for change
Westminster - Houses of Parliament

6 minutes

4 September 2026

UK Autumn Budget 2026: what could it mean for your finances?

With the Autumn Budget less than two months away, speculation is mounting. We look at what could change, what this could mean for your wealth, and how to prepare.

UK Autumn Budget 2026: what could it mean for your finances?
Access all our analysis

Sign up for insights

Subscribe for Rathbones news, insights, and upcoming events delivered directly to your inbox.

I’ve read Rathbones’ Privacy Policy, which explains how my personal information is used, and understand that I can always unsubscribe at any time.

GA Consent trigger

Ready to start a conversation?

Make a plan with one of our experts

Your investment journey starts today
Let's talk
Rathbones Logo
  • Important information
    • Important information
    • Financial Services Compensation Scheme
    • Complaints and the Financial Ombudsman Service
    • Privacy policy
    • Accessibility
    • Investor relations centre
    • Cookies
    • Update cookie preferences
  • Important information 2
    • Fraud: Reporting and preventing it
    • Client help hub
    • Interest rates
    • Climate reporting
    • Corporate governance
    • Modern Slavery Statement
    • Sitemap
    • Website status and updates
Address

Rathbones Group Plc
30 Gresham Street
London
EC2V 7QN

© 2026 Rathbones Group Plc
Incorporated and registered in England and Wales.
Registered number 01000403

Follow us
  • Facebook
  • Instagram
  • LinkedIn
  • X
  • Youtube
Also of Interest
  • Value of ESG in Adviser Investment Practices
  • Wealth Management E-Communications
  • Responsible Investment Transparency

The value of your investments and the income from them may go down as well as up, and you could get back less than you invested.

Wealth Management

You are leaving the {source} website
You are leaving the Rathbones {source} website and entering the Rathbones {destination} website.
Products, services and regulatory protections may differ between jurisdictions.
Would you like to continue?